
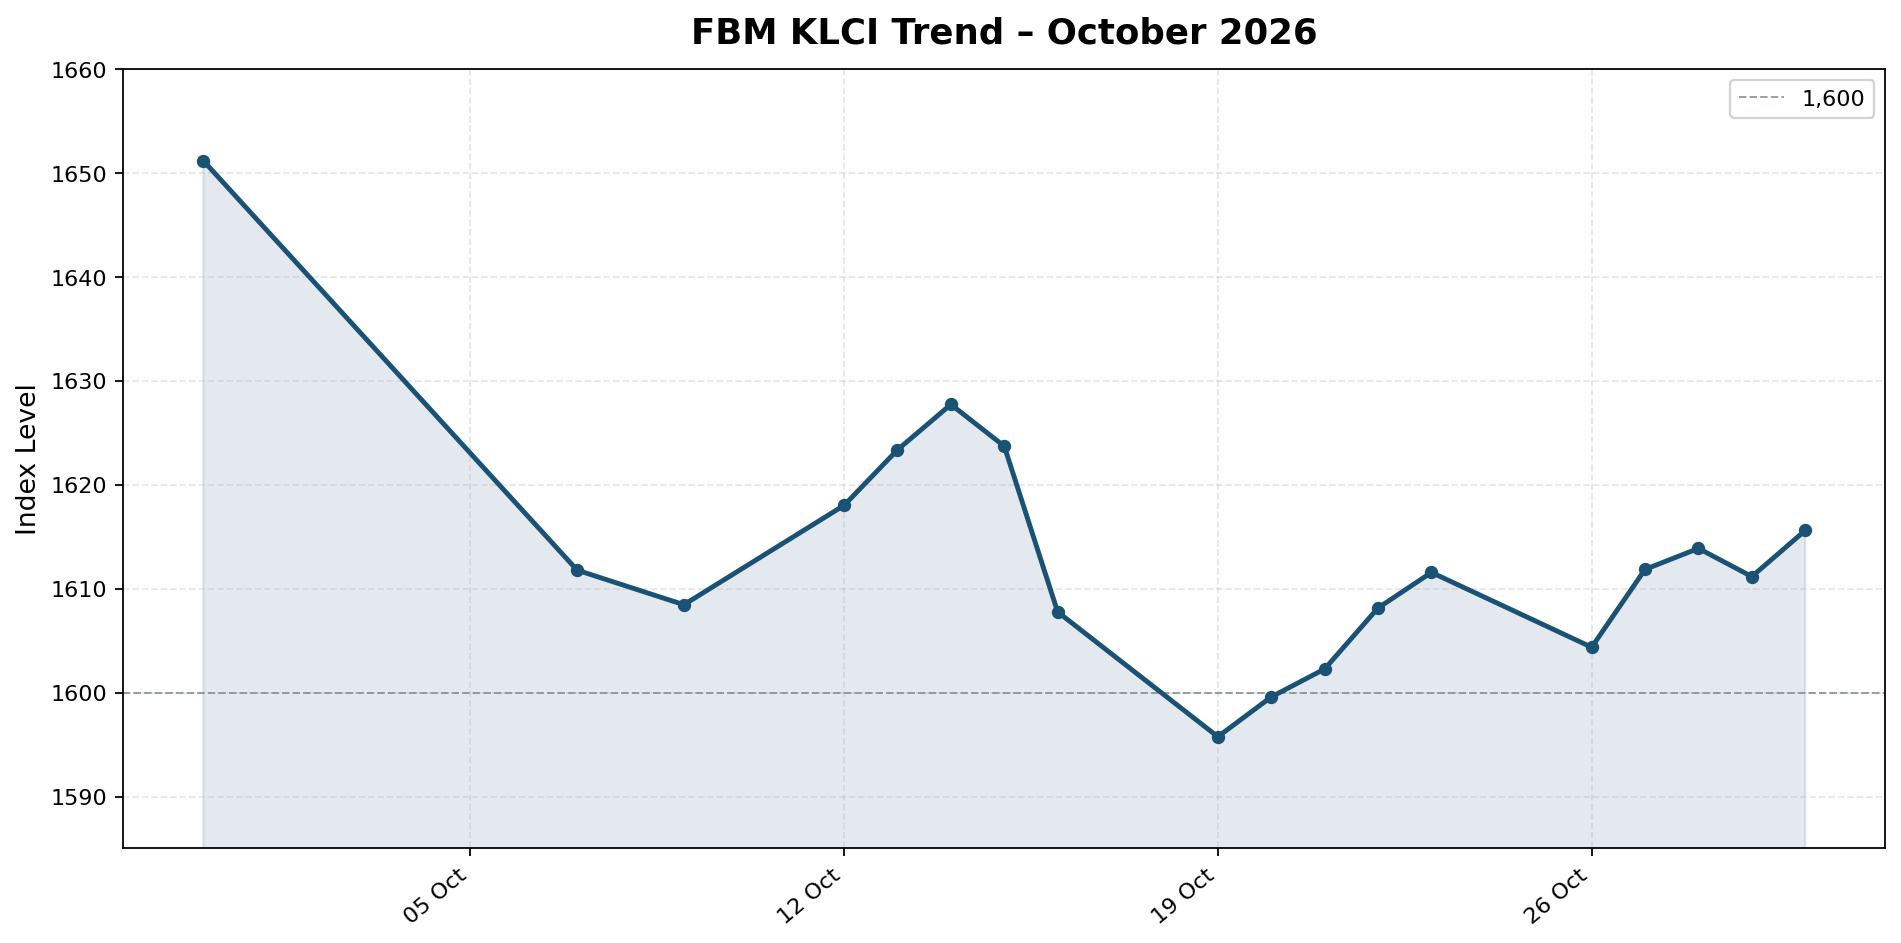
The FBM KLCI closed October 2026 at 1,615.60 on Friday, 30 October, after rising 4.44 points (0.27%) on the final session. For the month it fell 35.57 points, or 2.15%, from the end-September close of 1,651.17. The index spent much of the month under pressure, briefly trading below the psychologically important 1,600 level (lows around 1,595–1,599 in mid-to-late October) before a late stabilisation.
Year-to-date performance was roughly flat to modestly negative by month-end. Trading was characterised by persistent foreign selling, elevated oil prices tied to Middle East tensions, high US yields, and rotation away from technology/semiconductor names amid AI valuation concerns. Domestic support from local institutions and retail investors, plus selective strength in plantations and some banks, limited the downside.
Monthly Performance Snapshot
- Start of October (from end-Sept): ~1,651
- End of October (30 Oct): 1,615.60
- Monthly change: –2.15%
- Notable low: Below 1,600 mid-month
- Final week: Modest gain of ~0.25%
- Ringgit: Strengthened toward the end of the month, briefly touching near a two-month high around 4.05 against the US dollar
Market breadth was frequently negative. Foreign investors were net sellers of more than RM1 billion during October (HLIB data), continuing a multi-month trend of outflows. Local institutions and retail provided partial offset.
Movers and Shakers
Relative strength / frequent gainers
- Plantation heavyweights such as Kuala Lumpur Kepong and United Plantations (supported by commodity prices and selective buying)
- Nestlé (strong earnings-driven moves later in the month)
- Selected banks and utilities on bargain-hunting or month-end rebalancing days
- Some energy names when oil spiked
Pressure points / frequent losers
- Technology and semiconductor counters: Malaysian Pacific Industries, UWC, MI Technovation, Pentamaster and others repeatedly appeared among top decliners on AI valuation and risk-off days
- Genting group names after a rights issue announcement that triggered sharp sell-offs early in the month
- Occasional weakness in banks and selected industrials during foreign selling waves
Most active Zetrix AI remained a high-volume name throughout. Glove counters (Top Glove and others) and smaller speculative names also featured heavily in daily volume rankings.
Policy, Geopolitical and Macro Drivers
Oil and geopolitics (dominant theme)
Brent crude stayed elevated (frequently above US$100, with spikes toward US$110–114) amid US–Iran tensions and Strait of Hormuz risks. This supported some energy and plantation names but raised inflation concerns, kept yields high, and weighed on broader risk appetite. Malaysia’s status as a net oil exporter offered a partial buffer, according to research notes.
US monetary policy
The Federal Reserve held rates steady at its late-October meeting (after the September hike to 3.75–4.00%). Markets still priced the possibility of another hike later in 2026. High US Treasury yields (around 5%) and a strong dollar earlier in the month contributed to EM outflows, including from Malaysia. The ringgit’s late-month recovery reflected some reassessment of further Fed tightening.
Domestic factors
- Budget 2027 was tabled (expansionary but with the deficit targeted to narrow to 3.3% of GDP). Impact was viewed as largely neutral-to-mildly supportive for selected sectors.
- Announcement of the FBM KLCI expansion from 30 to 50 constituents (phased implementation starting 21 December 2026, with 20 new names added at 50% of final weight in Phase 1). Research houses (e.g., AHAM) described the weighting impact on existing constituents as manageable and the change as a better reflection of the domestic economy, including more tech exposure.
- Stronger-than-expected Q3 advance GDP (~5.3%) fuelled some speculation around a possible future BNM rate move, though no change occurred in October.
- Political calendar: Sarawak state assembly dissolution ahead of elections; Melaka polls set for 14 November. These added a layer of caution but were not the primary drivers.
- Q3 earnings season approached, with mixed early signals (Nestlé positive; cost pressures noted elsewhere).
Other market notes Foreign selling remained the clearest structural headwind. Month-end rebalancing and selective bargain hunting helped the index finish the month above its mid-month lows. Broader indices (FBM 70, Emas, etc.) were mixed-to-weaker on many sessions, reflecting mid- and small-cap pressure.
Outlook Carry-Forward
The October tape left the KLCI range-bound to soft, with 1,600 as the key near-term reference. Support sits near recent lows (~1,595–1,580), while resistance is layered toward 1,650–1,670 and the higher targets still cited by some houses (e.g., RHB’s 1,750 year-end). Oil, Fed guidance, foreign flows, the KLCI rebalancing, and Q3 results are the main variables into November.